
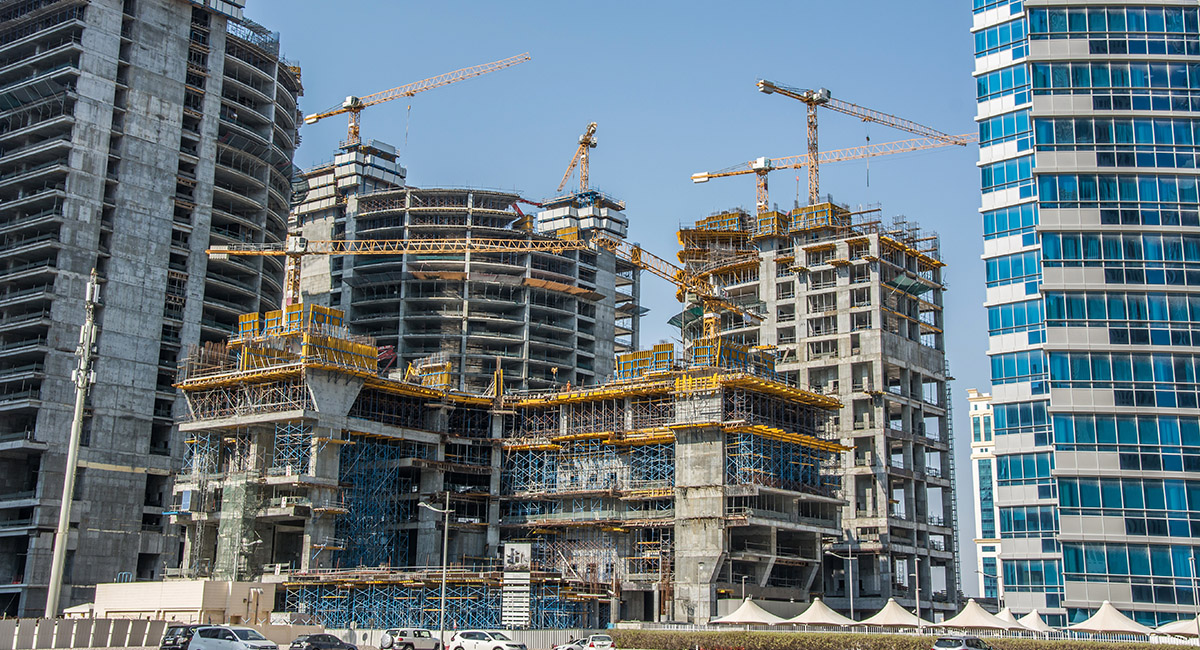
Housing construction in Canada remained positive in the first quarter of 2026, but the cycle continued to soften beneath the headline totals.
In centres with populations above 10,000, actual starts rose to 48,372 from 45,329 in Q1 2025 — a gain of 6.7 per cent. January was nearly flat year-over-year followed by stronger activity in February and March. The increase was led by multi-family construction, which rose nearly 11 per cent, while single-detached starts decreased about seven per cent.
Residential construction is increasingly driven by apartment and large multi-unit projects. These projects typically involve longer approval, financing and presale cycles, so current starts often reflect decisions made months earlier. As a result, the first quarter data is a better indicator of active construction more than current market confidence.
Completion data reinforces that lag. In centres with populations over 100,000, single-detached completions declined by about nine per cent, while multi-family completions increased by nearly seven per cent. Many of those units originated from projects conceived under different financing and demand conditions than those facing developers today.
Housing Starts by Province
British Columbia posted a modest decline, with starts falling three per cent. While Metro Vancouver rose sharply, several smaller markets moved lower. A few high-density projects can materially affect quarterly totals, especially when activity elsewhere slows. Vancouver remains active, particularly in apartments and rental projects, but it is still exposed to weak condo pre-sales, high land costs, construction pricing and tighter lending.
Alberta reversed after several years of strong growth, with starts down 16 per cent. Calgary and Edmonton fell 20 per cent and 17, respectively, suggesting the province is moving out of its accelerated expansion phase.
Saskatchewan also declined sharply, while Manitoba increased, helped by steadier activity in Winnipeg.
Ontario accounted for much of the national gain, with starts up 26 per cent. Toronto was slightly lower year-over-year, while several mid-sized markets posted large increases from smaller bases. The province’s stronger numbers do not necessarily indicate improving sentiment. Large projects already financed and approved continue moving into construction, while future launches face weak condo absorption, unsold inventory, high borrowing costs and elevated construction prices.
Quebec starts rose 11 per cent, supported by multi-family activity. Montreal remained central to the province’s construction cycle, though starts were lower year-over-year. Quebec City, Sherbrooke and Saguenay posted gains, mostly from smaller bases. As in Toronto and Vancouver, rental-oriented construction remains active, while financing and cost pressures limit replacement projects.
Atlantic Canada remained small in national terms and uneven by market. Nova Scotia declined, led by Halifax, while New Brunswick was basically flat. Prince Edward Island and Newfoundland and Labrador increased from modest bases.
The first quarter did not show a broad construction collapse. Starts remained above year-earlier levels and apartment construction continued carrying the national pipeline. But the data points to a market adjusting through lag.
Existing projects are still supporting current activity, while the conditions needed to launch the next wave of developments have become more challenging. The open question is whether enough viable projects are entering the pipeline to sustain current construction levels several years from now.
Housing Absorption by CMA
Across Canada’s major housing markets, the latest census metropolitan area (CMA) figures point less to a broad absorption problem than to a set of provincial mismatches between product type, price and buyer timing in removing units from the market.
Nationally, multi-unit housing is absorbing more successfully at completion than detached product. About 73 per cent of multi-unit units were absorbed at completion, compared with 64 per cent of completed detached homes. However, finished multi-unit supply is also higher. The CMAs ended the period with 11,783 completed and unabsorbed multi-unit units, versus 7,828 detached homes. That leaves multi-unit inventory at 10.6 months of supply, compared with 7.8 months for detached.
B.C. has the clearest multi-unit overhang. Vancouver closed the period with 4,054 completed and unabsorbed multi-unit units, Victoria with 846, Kelowna with 634, and Abbotsford-Mission with 213. These are not inactive markets. Vancouver absorbed 1,620 multi-unit units at completion and another 1,206 from existing inventory. The issue is the amount still left to clear. Vancouver’s multi-unit inventory stands at around 16.3 months, Victoria’s at 23 months, Kelowna’s at nearly 24.8 months, and Abbotsford-Mission’s at 80.1 months. High detached pricing adds another constraint, with average detached prices ranging from about $1.65 million in Victoria, to $2.59 million in Vancouver.
Alberta looks more like a high-volume market than a stalled one. Calgary completed 2,329 detached homes and 1,111 multi-unit units, absorbing 70 per cent and 63 per cent of detached and multi-unit completions, respectively. Its inventory remains moderate, at 8.4 months for detached and 8.5 months for multi-unit. Edmonton closed with 2,156 completed and unabsorbed detached homes — the largest detached stock — but that represents only six months of supply. Its weaker detached absorption at completion, 35 per cent, suggests more completed product is moving after completion rather than before or at delivery.
Ontario’s pressure is concentrated in detached housing outside Toronto. The city absorbed 85 per cent of detached completions and 94 per cent of multi-unit completions, though it still closed with 965 unabsorbed multi-unit units, equal to 16.4 months of supply. The more pronounced signal is detached inventory in surrounding and secondary markets: 75.4 months in Ottawa, 32.7 in Kitchener-Cambridge-Waterloo, 31 in Oshawa, 28.8 in London, 22.9 in Hamilton and 17.9 in Barrie. Several of those markets still show strong absorption at completion, so the problem appears to involve pricing, timing, product mix and carry-over stock rather than an absence of buyers.
Quebec is more contained. Montreal closed with 1,656 unabsorbed multi-unit units, but its multi-unit inventory is 12 months, below the more stressed B.C. markets. Quebec City, Sherbrooke, Trois-Rivières and Saguenay show shorter stock positions and lower absolute volumes.
Atlantic Canada remains limited in scale. Moncton, Fredericton, Saint John and St. John’s mostly sit below double-digit inventory. Halifax is the main exception, carrying 13.6 months of detached supply at the region’s higher price point.
Renovation Spending Gains Ground
First-quarter figures show a construction market changing by category rather than moving in one clear direction. New multi-unit residential construction remains the largest national new-build segment, but the sharper movement is in single-dwelling work, where investment is shifting toward renovation and away from new construction.
That shift changes the kind of work moving through the market. New single-family construction generally follows a more predictable sequence, with crews moving from site work and framing through rough-ins, finishing and handover. Renovation work is less orderly. Contractors are often dealing with occupied homes, older mechanical systems, partial demolition, hidden deficiencies and customer decisions made after the job has started. Stronger renovation spending favours companies that can manage smaller, more variable projects without losing control of scheduling, labour allocation or margin.
Multi-residential construction continues to absorb substantial capital. Apartments, condominiums and other multi-unit projects carry long planning cycles, larger financing commitments and more complicated procurement than single-family builds. The modest national increase in this category does not suggest easier operating conditions, but it does show that large residential projects remain central to construction activity.
Commercial construction is more balanced between new buildings and renovation. The renovation side appears to be gaining importance, which is consistent with more work in tenant improvements, interior reconfigurations, building upgrades and repositioning projects. For mechanical, electrical, flooring, millwork, glazing and interior finishing trades, this type of spending can keep crews active even when owners are more selective about committing to full new-build projects.
Provincial data shows why national averages need careful handling. Ontario remains the largest market but its residential activity softened while non-residential spending held steadier. B.C. showed broader strength, with residential renovation rising alongside new residential construction, a combination that could tighten availability among trades that serve both markets.
Alberta’s pattern was different again: stronger new construction and non-residential activity, but a sharp pullback in residential renovation. Quebec saw renovation take a larger role in residential work while non-residential investment declined. Manitoba and Saskatchewan posted gains across the board, with renovation still ahead of new residential construction. Atlantic Canada was mixed, with weakness in residential new builds offset by gains elsewhere.
The first quarter data points to a market reallocating work. Contractors and manufacturers will need to read those shifts early in estimating, staffing, procurement and project selection, before they show up as pressure on the job site.
Tyler Holt is the editor of Wood Industry magazine. He has a master’s degree in literature and publication, and years of experience in the publishing and digital media industry. His main area of study is the effect of digital technologies on industrial and networked production.