

Do the right thing
Avoid conflict through competence, passion and customer service
Something can always go wrong on a flooring project. Sometimes even catastrophes happen. Mistakes can lead to ruined floors, angry clients and messy disputes. Having a plan in place to deal with potential disasters is crucial. Such plans can involve legal protections such as insurance. Yet, more often than not, the best risk management plan in flooring involves one simple rule: Treat the client right. The rest often takes care of itself.
That’s what Canadian flooring professionals tell us is the best approach to handling problem projects. “You probably see a lot more lawsuits in the States than you do here. I think Canadians tend to handle things differently,” says Nick Kaplanis, project/sales/customer-service manager at Nufloors in Langley, B.C. “I honestly don’t think we’ve had a major incident, and it’s because of our comprehensive approach to customer service.”
That’s not to say his company doesn’t have policies in place in case a major catastrophe does happen. According to Kaplanis, “We have extensive liability insurance, which means we’re covered if we’re responsible for something accidental. But if we’re at fault, we make it right with the customer. We’ll pay for it — whatever it takes.”
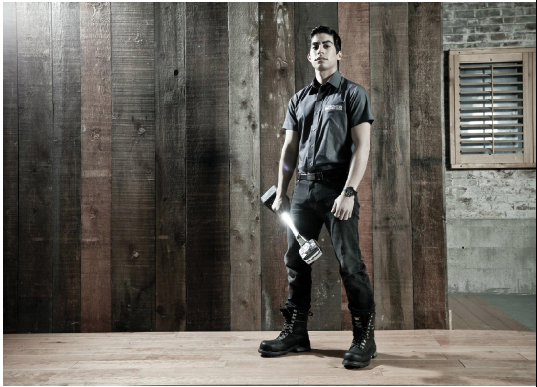
including Frontier’s lead installer, Elmer Cabrera.
Being cynical is not hard these days. Governments engage in shutdowns, corporations receive undeserving bailouts, and scammers seem to be around every corner reaching for our wallets. So what Kaplanis has to say about his business approach might seem uncommon, but he believes it’s crucial to success in floorcovering. He says, “Honesty is the best policy.”
“We truly bend over backwards to make the customer happy,” Kaplanis says. “You’re in trouble if you don’t. Believe me. We start at the beginning. Our sales staff is trained to go through the contract with the customer so we manage expectations right from the start. We tell the customer what we’re responsible for, and what we’re not responsible for. And the customer appreciates this upfront approach.”
At the heart of Kaplanis’s strategy for avoiding catastrophes with flooring projects is Gerry Barron, Nufloor’s installation coordinator. According to Kaplanis, “Gerry is crucial. He not only acts as our technical liaison with the customer, which he’s great at, but he’s very good with our installer contractors, and he even sets me straight sometimes, too. Gerry helps us avoid problems. I recommend someone like him for every store.”
Kaplanis believes such a project point-man is rare in the industry. In fact, he says he’s the only store he knows of in the Nufloors chain to hire someone like Barron. Yet the practice appears to be catching on. In fact, for Frontier Flooring Services in Vancouver, B.C., at least two people serve as point-men for many of the company’s installation projects.
Frontier’s president, Hector Cabrera, explains, “My brother, Elmer, is a project coordinator who handles all key projects. Derick Heun is our project manager and often handles issues with our clients. Between the two of them, as well as other members of our team, we go to great lengths to do the job right, satisfy the customer, and avoid unnecessary problems.”
It has taken Frontier Flooring a number of years to perfect its approach to serving the customer, and it all started when the father, Andres, fled from war-torn El Salvador in 1990 to make a new life for himself and his family in Canada. Andres started work as a floor installer on his second day as a resident in Canada, and the rest is part of family history.
Hector Cabrera expands on some of this history and how it has shaped the company today: “My father did mostly commercial installation work. Along with my brother, Elmer, we grew up in this business. But I found the commercial side to be rather cold. The personal connections between people seemed to be lacking — between the client and the contractors, and so on.”
While Elmer stayed in the business and became an installer, just like dad, Hector went on to university. His work experience after graduation taught him a lesson about doing business. He says, “I ended up surrounded by engineers who often did work on contract, and the personal camaraderie was great. That was lacking in flooring installation, and I wanted to change that.”
And change he did. He went back into flooring to run Frontier, alongside dad and brother. In contrast to the father’s grounding in commercial installation, Hector decided to take Frontier Flooring into the residential sector. He says, “I believe it’s in residential flooring where personal relationships have a greater chance to flourish. This personalized approach is the foundation of how we now do business.”
In fact, Frontier has developed a very unique approach to all facets of its business. Hector Cabrera very much sees his business not so much as a flooring company but as a collection of artisans delivering unique projects to appreciative clients.
He says, “You need to stand out in the flooring business. You not only need to give clients a reason to hire you, you need to give installers a reason for wanting to work with you. So we have incorporated this artisan approach to flooring installation. We train our installers to be artisans: skilled craftsmen who are proud of their creations. In turn, the clients appreciate this approach and the kind of effort that goes into our projects.”
For both Kaplanis and Cabrera, a customer-oriented approach towards flooring installation helps avoid potential catastrophes. Yet it can’t be the only approach in dealing with risk. Just like Kaplanis at Nufloors, Cabrera invests in a liability insurance plan at Frontier Flooring, too.
He says, “It depends on the specific plan you have, but good liability coverage can run for a few thousand dollars a year. It’s worth the investment. Even though we could get by with $2 million in coverage, we’ve gone with $ 5 million because we full expect to grow and want to be ready for all contingencies.”
Although most insurance companies offer template plans to customers, Cabrera believes it’s important to tailor any plan to your company’s specific needs. In fact, Frontier Flooring obtained the services of a risk-management firm to do just that. Cabrera says, “We’re not a ski resort where accidents often happen, so this risk-management firm isn’t on retainer. But we used them to help us assess our insurance needs, so we now have a plan specifically for us.”
At both Nufloors and Frontier, the liability insurance covers all the installers — for accidental occurrences — not for incompetence. For example, liability insurance would cover the replacement of a floor if an installer accidentally dropped a toolbox on it from upstairs. However, liability insurance would not cover a floor replacement if it resulted from the use of improper adhesive or an improper gap between floor and wall.
According to Garry Manovich, manager of commercial property for insurance service provider SGI Canada, flooring contractors and installers can’t always rely on retail stores to provide proper insurance. He says, “There is a common misunderstanding that installers are covered by the stores that hire them …. As independent contractors, installers are responsible for their own insurance.”
In other words, while companies such as Nufloors and Frontier provide insurance for their contractors, other stores might not. In such cases, insurance companies sometimes provide coverage specifically tailored to small construction contractors such as flooring installers. Manovich adds, “The advantage of having liability insurance [for installation contractors] is that not only will the insurance company compensate third parties for injuries or damages they cause, the insurance company will also hire a lawyer and pay to defend the action.”
For Paul Maugeri, underwriting team manager for State Farm Canada, an insurance policy does help any business operation to protect itself from financial loss due to possible legal action. However, as already mentioned, it’s not the only approach to deal with risk. According to Maugeri, “Hiring skilled and knowledgeable employees, providing proper training, ensuring proper workplace safety, ensuring proper and ethical business practices are followed” are all necessary, too.
While interactions with the client are part of the risk assessment, so too is dealing with the manufacturer of a flooring product. Kaplanis is currently dealing with such a situation. He says, “So, we installed a hardwood floor, and the customer immediately complains of splintering. We then find out from the manufacturer that shoes should be worn on this floor. It’s the first we heard of such a thing.”
Kaplanis continues, “The first thing we did is set things straight with the customer. We replaced the floor and paid for it. Now we’re talking to the manufacturer. We think we should receive compensation from them. It still hasn’t been settled, but we’ll keep talking, and hopefully we don’t have to take it to court. We haven’t had to resort to such an action as long as I’ve been here.”
Kaplanis believes that much of the litigation in the flooring/construction sector occurs between the insurance companies themselves, and doesn’t involve the contractor, customer or the manufacturer. He says, “They end up fighting among themselves, which is fine by me. I’d prefer they sort it out rather than having us jeopardize the relationships we’ve developed with clients and suppliers.”
Indeed, avoiding conflict appears to be the Canadian way; a trait that our flooring sector appears to have adopted, too. A two-pronged approach to managing risk has managed some success. On the one hand, the legal policies and documents need to provide legal protection. But, on the other hand, there is no substitute for having a passion and pride for what you do, a desire to satisfy the customer, and a willingness to just do the job well.